IN JUNE 2022, Emily Garrett had just moved from Michigan to Mississippi to live with her best friend. That’s when the 22-year-old began to experience perplexing symptoms. Her face swelled up. She suffered frequent migraines. Dark spots floated across her vision. Then one day, she started vomiting neon green fluid, so she headed to the emergency room.
In September 2022, after numerous tests, physicians diagnosed Garrett with Hodgkin lymphoma, a cancer that develops in the lymphatic system, the network of nodes and vessels that help the body fight infection. By then, Garrett had three tumors, the largest of which was roughly the size of a softball and pressed against a crucial heart valve that controls how blood flows to the rest of the body. “My doctors said I was within days of the disease probably making my heart fail or causing a stroke,” she says.
Garrett, who had just graduated from community college and was working as a makeup artist, was initially hospitalized for 40 days. Then, after four days at home, she was admitted to the hospital again for another 19 days. Her chemotherapy infusions, which started in the hospital, continued every two weeks for seven months and were followed by a month of radiation. Garrett had insurance through the health insurance marketplace, established by the Affordable Care Act, but she knew it wouldn’t cover the cost for all her care.

Diagnosed with Hodgkin lymphoma at age 22 in September 2022, Emily Garrett had two lengthy hospital stays. She started receiving collections calls soon after. Photo courtesy of Emily Garrett
The calls prompting her to pay outstanding bills or to make minimum payments started about two months after her first hospital admission. By the end of 2022, an overdue bill of roughly $2,400 had been sent to a collection agency. The billing calls were “never ending,” she says. “There’s constant reminders every day.”
Daunting Costs
Adults ages 20 to 39 make up just 4% of cancer diagnoses in the U.S. each year, but research suggests that these young adults experience disproportionately greater financial fallout from their treatment compared with older adults. A 2022 study published in Cancer, which was based on 311 survey responses from adult cancer survivors of all ages, found that half of adults between ages 18 and 39 experienced severe financial toxicity. By comparison, 40.7% of adults between ages 40 and 64 and 9.6% of people 65 and older reported severe financial stress.
In addition, many young adults are diagnosed with fast-growing cancers, which often require multiple treatment modalities, including chemotherapy and radiation along with surgery, says Fumiko Chino, a radiation oncologist at the University of Texas MD Anderson Cancer Center in Houston. “You typically are going to need a full-court press to treat the disease and hopefully cure the disease,” says Chino, who has studied the financial burden of cancer in young people. She notes that young people may not have comprehensive health insurance to keep them afloat as they make their way through treatment.
In addition, the diagnosis may hit when young adults are only partway through their education or are in the early years of building their careers, with less savings to fall back on than older adults, Chino says.
This population can face additional related costs, including the expense of fertility preservation, which may not be covered by insurance. In addition, young adults typically need ongoing monitoring to watch for cancer recurrences or treatment-related issues, Chino says. The financial impact can cast a long shadow over other aspects of life, she adds. For example, a person who carries a lower credit score after falling behind on medical bills may not be able to get a home loan. “Certainly, every study that I have evaluated shows that [financial toxicity] is worse in this population and may be, more importantly, more durable in this population,” she says.
Chino oversaw a 2022 research study published in the Journal of Cancer Survivorship based on a survey of young adults between 15 and 39. The study found that 45% of young adult cancer survivors had taken on credit card debt, 42% had borrowed money and 23% lacked money for basic necessities. Roughly 1 in 3 of those who filled out the surveys received calls from debt collectors. “For the most part, survivors were really struggling,” says Bridgette Thom, the study’s lead author and a cancer survivorship researcher at Lineberger Comprehensive Cancer Center at the University of North Carolina at Chapel Hill.
Nearly 14% of adults ages 19 to 34 lack health insurance, compared with just over 7% of adults ages 55 to 64, according to a KFF analysis of federal census data from 2023. Moreover, figuring out the complexities of insurance and billing may be “even more challenging for younger patients who don’t have the experience in dealing with this,” Thom says. “This might be their first encounter with the health care system.”
With growing awareness of this population’s financial vulnerability, some hospitals are offering financial resources and educational opportunities targeted to younger adults. In addition, some hospitals offer charity care that waives at least part of the bill for those who meet financial and other criteria. But there are not nearly enough programs to meet the need, Thom says, and it’s the patients who typically shoulder most of the burden.
Reducing Financial Strain
Young adults often need to be persistent and proactive to keep one step ahead of financial distress. Monica Bryant, an attorney and chief mission officer at Triage Cancer, a nonprofit that provides legal education for people with cancer and their families, encourages young adults to talk with health care providers about any worries about paying their bills.
Social workers or other staff members at hospitals can often connect patients to financial assistance resources and provide information to improve financial health, Bryant says. She encourages people receiving treatment to also ask about financially feasible and practical treatment alternatives. For instance, the doctor may be able to start a patient on oral chemotherapy rather than more time-consuming infusion sessions that can put a patient’s job at risk, she says.
Hospital charity care programs may also be worth exploring. “They’re more generous than people think,” says Jared Walker, founder of Dollar For, a nonprofit that helps people apply for medical debt forgiveness. He says someone earning annually as much as 400% of the federal poverty limit—$62,600 for an individual and $84,600 for a couple—may still qualify for charity care assistance. To learn about these programs, people can enter their medical center’s name and the term “financial assistance policy” into an online search engine, he adds.
Young adults may also want to become better acquainted with the nuts and bolts of their insurance policy, including the amount of money they must pay for covered services in a calendar year before insurance picks up the rest of the tab, Bryant says. Be sure to verify whether your hospital and health care providers are within the insurer’s network.
Keep in mind that health care organizations may bill the patient before the insurer can review the claim, Bryant says. “I think people get a bill and they think that’s what they owe. That patient may not actually owe $8,000.”
Insurance plans have a cap on how much people can be charged out of pocket for covered health care, but what that maximum is can vary depending on coverage.
Healthy young adults may opt for insurance plans with low monthly premiums because they seem more affordable, says Monica Bryant, chief mission officer at Triage Cancer. However, in exchange for lower premiums, these plans often come with higher out-of-pocket costs.
Once a person is diagnosed with cancer, it’s highly likely they will meet their out-of-pocket maximum, Bryant says. That’s the total amount that a person will need to pay before insurance covers the full cost of medical expenses, although the patient will still be on the hook for their monthly premium.
To determine their insurance plan’s out-of-pocket maximum amount, people can log into their insurance company’s portal or call the insurance provider. For instance, the out-of-pocket maximum for plans purchased through the Affordable Care Act insurance marketplace can’t be higher than $9,200 for an individual in 2025 (and may be lower depending upon the plan).
Other insurance policies, such as ones offered through an employer, may exclude certain costs from counting toward that maximum figure, says Bryant. As one example, an individual’s annual deductible may not count toward the out-of-pocket maximum.
Keep in mind as well that the out-of-pocket maximum resets with each plan year, which could matter depending on when you are diagnosed with cancer and when you receive treatment.
Once the out-of-pocket maximum is reached, patients should not pay bills for service from in-network providers for the rest of the plan year—even if the amount is small, such as a $30 copay for a doctor’s visit. That money should stay in the patient’s wallet for groceries and other necessities, Bryant says.
Bryant suggests that people hold off on paying any bills until the insurer provides an explanation of benefits, a statement that details what care the insurer will cover and how much the patient is financially responsible for. If the insurer hasn’t provided the summary, let the hospital or provider know, she says. Request that the hospital or provider push back the payment date or, alternatively, add a note in your file that the explanation of benefits hasn’t arrived. While mounting treatment bills and related calls are unsettling, Walker advises young adults to sort out precisely how much they owe and a payment approach before making any rash financial decisions. “I tell people, ‘Take a deep breath. You have some time,’” Walker says. “Don’t panic and put it on a credit card.”
Another time-consuming but key step: Take a close look at bills to check for inaccuracies, Walker says. If information about the services provided is missing, you should call and ask for clarification, including requesting an itemized bill. If a treatment charge doesn’t look right, don’t hesitate to call for clarification. “Ask them, ‘What is on this bill? What are these services?’” Bryant says.
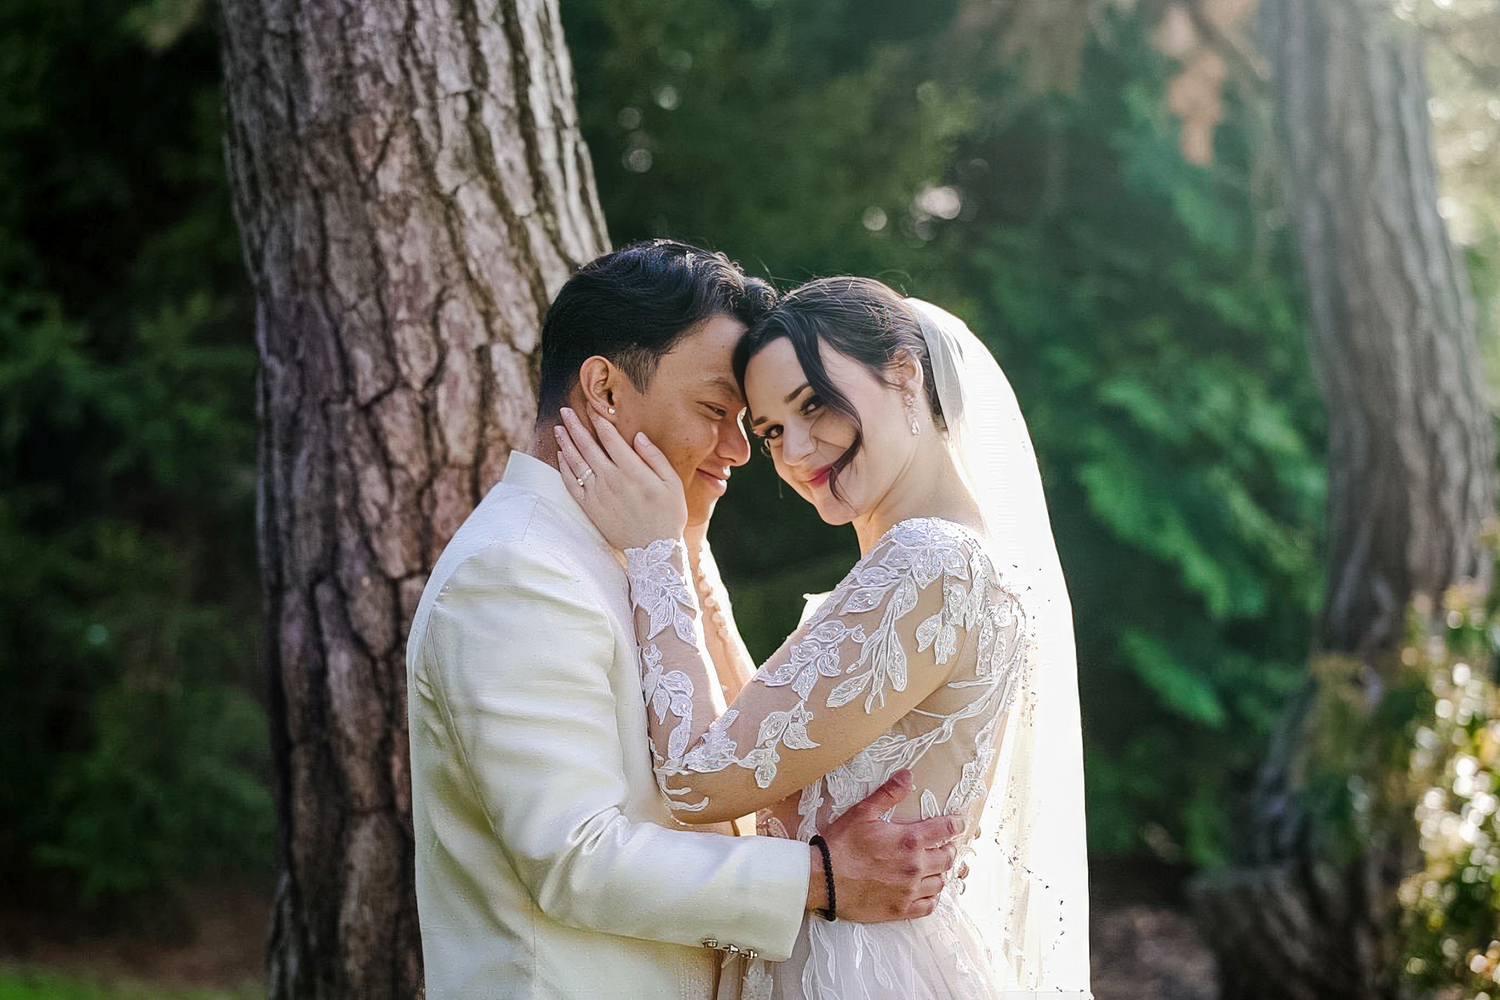
Shortly after her wedding in 2020, Megan Rivera was diagnosed with leukemia. She recalls sorting through bills and negotiating payment plans while propped up in her hospital bed with a computer tablet on her lap. Photo by Katie Merkle Photography
Additionally, patients can negotiate with health care providers for short-term relief, such as setting up a payment plan, Walker says.
“You have to put in the work,” Bryant says. “And it’s not fair because [they’re] putting a lot on the plates of people who are already dealing with a lot.”
Importance of Self-advocacy
After Garrett’s diagnosis, her sister established a crowdfunding account to assist with the accumulating bills. Her father covered her rent until Garrett had finished chemotherapy treatment and returned to work, even though she wasn’t quite physically ready. “He couldn’t afford to do it anymore,” she says, adding that she was grateful for the help.
Even after insurance covered her medical expenses, the bills kept coming. Garrett applied for medical debt relief through Dollar For, in the hope of getting at least part of her outstanding bills waived. With the group’s assistance, she got a portion of her bills eliminated.
Like Garrett, Megan Rivera also started fielding billing-related calls several weeks after her leukemia diagnosis in May 2022. Rivera and her new husband, Kris, had just returned from their honeymoon when the 26-year-old registered nurse went to the emergency room with symptoms of fatigue and weakness and was abruptly hospitalized.
Rivera had a high-deductible insurance plan, so she had to meet her deductible of $8,700 before insurance started covering the cost of her care, which included a bone marrow transplant. Money was already tight at the time. The couple had footed most of the bill for their wedding and had purchased a home in the suburbs of Philadelphia in 2020.
Rivera recalls sorting through bills and negotiating payment plans while propped up in her hospital bed with a computer tablet on her lap. Eventually, she set up monthly payments that ranged from $100 to nearly $200 at each of the hospitals where she received care. Along the way, she filled out a lot of applications for assistance that didn’t go anywhere.
“You really have got to do sleuthing and call,” says Rivera, whose mother and aunt helped to make some of these calls. “If you’re trying to get help, it takes up a lot of time.”
Tapping Support Networks
Before Rivera had her bone marrow transplant in October 2022, she and her husband decided to pursue in vitro fertilization, which resulted in two embryos. The couple applied most of the $14,390 that friends and family raised through a crowdfunding site to pay the $10,500 bill.
Rivera’s mother helped her pay for groceries and gas, and family members pitched in when they could. But by the summer of 2023, Rivera and her husband were struggling to pay everyday bills, including the mortgage on their home. “We knew that there was a possibility that we could lose it,” Rivera says.
Organizations provide assistance to help manage the financial costs young adults with cancer face.
The following organizations offer assistance for medical bills, living expenses or other related costs for adolescents and young adults (AYAs):
Blood Cancer United, formerly the Leukemia & Lymphoma Society, offers scholarships up to $7,500 to cover tuition for vocational, trade, or two-year or four-year undergraduate programs for people who are diagnosed with blood cancer at age 25 or younger.
Dollar For helps people, including AYAs, navigate and access a hospital’s debt or bill forgiveness programs.
Livestrong Fertility teams up with fertility clinics that agree to provide discounted fertility preservation services, along with free or reduced-cost medication, for people with cancer whose treatment threatens their future ability to have children.
The SAMFund, part of the Expect Miracles Foundation, provides financial grants to AYA cancer survivors for expenses like rent, utilities, student loans, medical bills and fertility preservation.
Team Maggie’s Dream provides financial assistance to young women and men for preserving eggs and sperm.
Triage Cancer provides legal and financial information, including education about disability insurance, employment issues and managing debt.
The Ulman Foundation supports AYAs affected by cancer through housing, scholarships, community building and navigation services.
She applied for and received a grant from the SAMFund, part of the Expect Miracles Foundation, which covered two months of their mortgage. She also worked with Dollar For to apply for medical debt relief, which erased $10,600 from one hospital bill.
Financial resources for young adult cancer survivors are patchwork at best, Thom says. In addition, people who receive cancer treatment may feel too depleted to seek out financial assistance.
People with cancer should try to lean on friends and family who often are looking for ways to help, Thom and Bryant say. For example, a trusted friend or family member who accompanies a young adult to the appointment can take notes, so it’s easier to later verify if billing details are correct, Thom says.
Friends or family members can also organize medical bills and match them with any related explanation of benefits forms, Bryant adds. Even just sitting on hold with the health care organization or insurer and handing over the call once someone picks up can be a big help. “Energy is finite,” Bryant says. “Any place where you can save some energy is helpful.”
Although Garrett and Rivera have completed treatment, neither see an end for their financial stress.
Garrett still has an outstanding hospital balance of $17,000 for years of medical care. She also will need an $8,000 PET scan every three months until 2028. For that, she’s on the hook for roughly 20% of the cost, based on her current insurance plan. It’s a hefty price tag, but one that Garrett is willing to pay to protect her long-term health. Her lymphoma, she says, “has a really high recurrence rate. And also because I did radiation and chemo, I have a really high likelihood of getting other cancers.”
Cancer Today magazine is free to cancer patients, survivors and caregivers who live in the U.S. Subscribe here to receive four issues per year.